How to Build Credit in Switzerland: A Practical Guide for Residents
Advertisement
Learn how credit works in Switzerland, what the ZEK system means, and practical steps to build a strong financial profile as a resident.
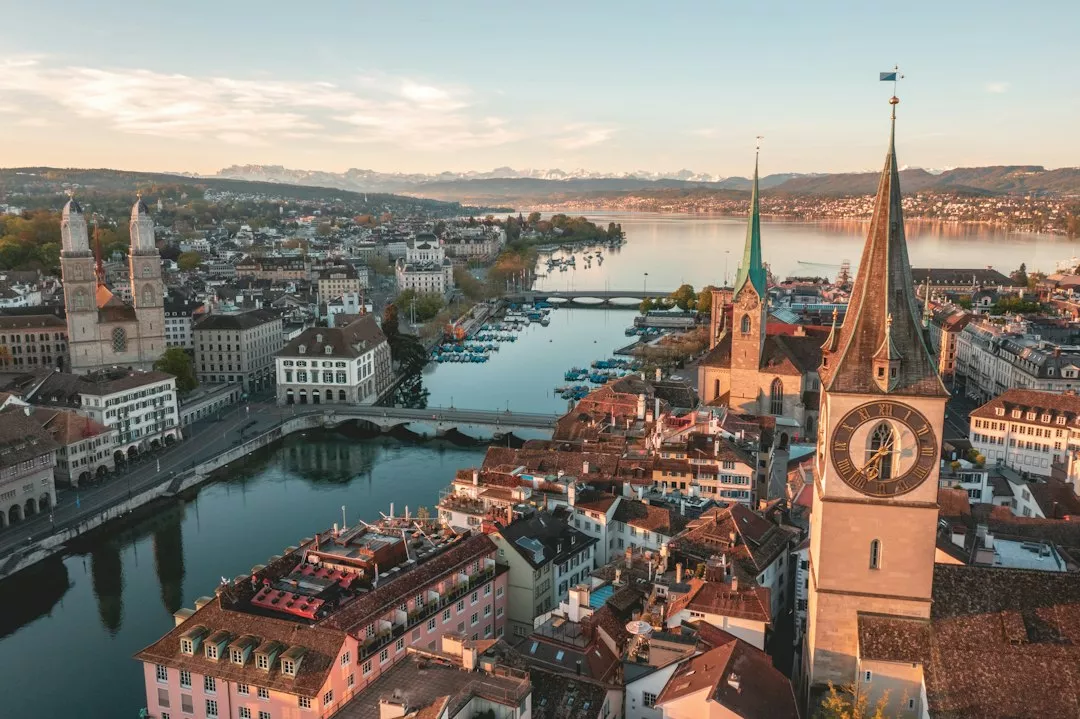
Switzerland has one of the most financially stable environments in the world, but for newcomers and even long-term residents, understanding how credit and financial reputation work here can be surprisingly confusing. Unlike many other countries, Switzerland does not use a single universal credit score. Instead, it relies on a network of data-sharing systems and behavioral signals that lenders, landlords, and service providers use to assess your financial reliability. This guide breaks down how the Swiss credit system works and what you can do to strengthen your financial standing over time.
How the Swiss Credit System Actually Works
In Switzerland, creditworthiness is evaluated primarily through the ZEK (Zentralstelle für Kreditinformation), a central credit information system used by Swiss banks and lenders. The ZEK stores data about existing loans, credit cards, leasing agreements, and any payment problems associated with those products. When you apply for a loan or a credit card, participating institutions check the ZEK database to assess whether you have had financial difficulties in the past.
Separately, the IKO (Informationsstelle für Konsumkredit) tracks consumer credit inquiries specifically. Both systems are governed by Swiss data protection law, and you have the right to request a copy of your own data held in these registries. Knowing what information is stored about you is an important first step before applying for any credit product.
There is also the Betreibungsregister — the debt collection register — which is publicly accessible and records any unpaid debts or formal collection proceedings made against you. A clean Betreibungsregister extract (Betreibungsregisterauszug) is often required when renting an apartment or applying for a mobile phone contract. This makes it one of the most practically important financial documents in everyday Swiss life.
Why Your Financial Reputation Matters Beyond Loans
Many residents underestimate how broadly financial reputation affects daily life in Switzerland. Landlords routinely request a Betreibungsregisterauszug before offering a rental contract. Mobile phone operators check it before granting a postpaid plan. Some employers in the financial and public sectors request confirmation of financial soundness as part of hiring due diligence.
This means that maintaining a clean financial record is not just about getting a bank loan — it touches nearly every major life decision. Understanding and managing your profile from the beginning saves you significant inconvenience later.
Practical Steps to Build a Strong Financial Profile in Switzerland
1. Open a Swiss Bank Account Early
Having an established relationship with a Swiss bank is the foundation of your financial profile. Major retail banks such as UBS, Credit Suisse (now integrated into UBS), PostFinance, Raiffeisen, and Cantonal banks all offer standard current accounts. For a broader look at Swiss banking options, our PostFinance Switzerland Review and ZKB Switzerland Review can help you understand what different institutions offer.
A bank account demonstrates residency stability and provides a base from which to access other products. Some banks may ask for a residence permit, proof of employment, and a local address. Be prepared with these documents when visiting a branch or completing an online application.
2. Use a Credit Card Responsibly
Once you have a bank account, applying for a credit card linked to that institution is one of the most effective ways to establish a positive credit record in Switzerland. When you use a credit card and consistently settle the full balance each billing cycle, this behavior is reflected in ZEK and IKO data as reliable and low-risk.
Avoid carrying a revolving balance where possible, as interest charges on Swiss credit cards can be significant. The key principle is simple: spend within your means and pay on time, every time. Missing a payment — even once — can generate a negative entry that stays in the ZEK system for a defined period. Always check the current terms with your card issuer so you understand exactly when payments must clear.
3. Avoid Unnecessary Credit Applications
Each formal credit or loan application made in Switzerland is typically logged in IKO. Multiple applications within a short period can signal financial instability to lenders, even if each individual application is declined or withdrawn. Be selective: research products thoroughly before applying, and only submit an application when you are genuinely ready to proceed. Our Julius Bär Switzerland Review and Kantonalbank Switzerland Review are useful starting points if you are comparing banking and credit options.
4. Keep Your Betreibungsregister Clean
This is perhaps the single most important habit for Swiss residents. Pay every bill — utilities, health insurance premiums, taxes, rent — on time. Swiss creditors are relatively quick to initiate formal debt collection proceedings compared to some other countries, and any such proceeding is recorded in the Betreibungsregister, even if you later settle the debt. The record remains visible for a set number of years after the event.
If you are going through a difficult financial period, contact creditors proactively and request a payment plan before a formal collection notice is issued. Many providers, including insurance companies and utilities, are willing to arrange installments if approached early.
5. Manage Your Health Insurance Premiums
In Switzerland, mandatory health insurance (Krankenkasse) is one of the most common sources of unpaid debt, particularly for newcomers who find the premiums unexpectedly high. If you qualify for premium subsidies (Prämienverbilligung) from your canton, apply as soon as you are eligible — failing to claim subsidies you are entitled to and then struggling to pay full premiums is a situation worth avoiding.
Review your Krankenkasse annually during the open enrollment period and consider switching to a more affordable insurer or deductible level. Lower premiums reduce the financial pressure on your monthly budget and make consistent, on-time payment easier to maintain.
Request Your Own Data — It Is Your Right
Swiss data protection legislation gives you the right to request a copy of the data held about you in both the ZEK and IKO registries. This is a straightforward process and carries no negative consequences. Reviewing your own file allows you to confirm that the information recorded is accurate and that there are no erroneous entries from old accounts or resolved disputes.
If you find inaccurate data, you have the right to request a correction. Contacting the relevant registry directly and providing documentation of the error is the standard procedure. Keeping your records accurate is just as important as building positive behavior over time.
Building Credit Takes Consistent Behavior Over Time
There is no shortcut to building a strong financial profile in Switzerland. The system rewards consistent, responsible behavior: paying bills on time, using credit products within their intended scope, and avoiding unnecessary debt. Lenders and landlords are not looking for perfection — they are looking for reliability and stability.
For expatriates, the process can feel slow at first, particularly if you are accustomed to a credit scoring model from another country that does not transfer. Be patient, start with the basics — a bank account, a clean Betreibungsregister, and a responsibly used credit card — and build from there. Over time, a well-managed financial profile opens doors to better loan terms, easier apartment applications, and a broader range of financial products.
Key Takeaways
- Switzerland uses the ZEK and IKO systems rather than a single credit score — understand what is recorded in each.
- The Betreibungsregister is publicly visible and affects your ability to rent an apartment, sign a phone contract, and more.
- Open a Swiss bank account early and use any credit products responsibly, paying balances in full and on time.
- Avoid multiple credit applications in a short timeframe.
- Request your own data from ZEK and IKO to verify accuracy — it is free and has no negative effect on your profile.
- Manage health insurance premiums carefully, as unpaid premiums are a common source of debt collection proceedings.
Building a solid financial reputation in Switzerland is entirely achievable with the right habits and a clear understanding of how the local system works. Start early, stay consistent, and your financial standing will reflect the effort.
Daniel Westberg
Financial journalist covering Nordic credit cards, banking products, and consumer finance across Scandinavia.